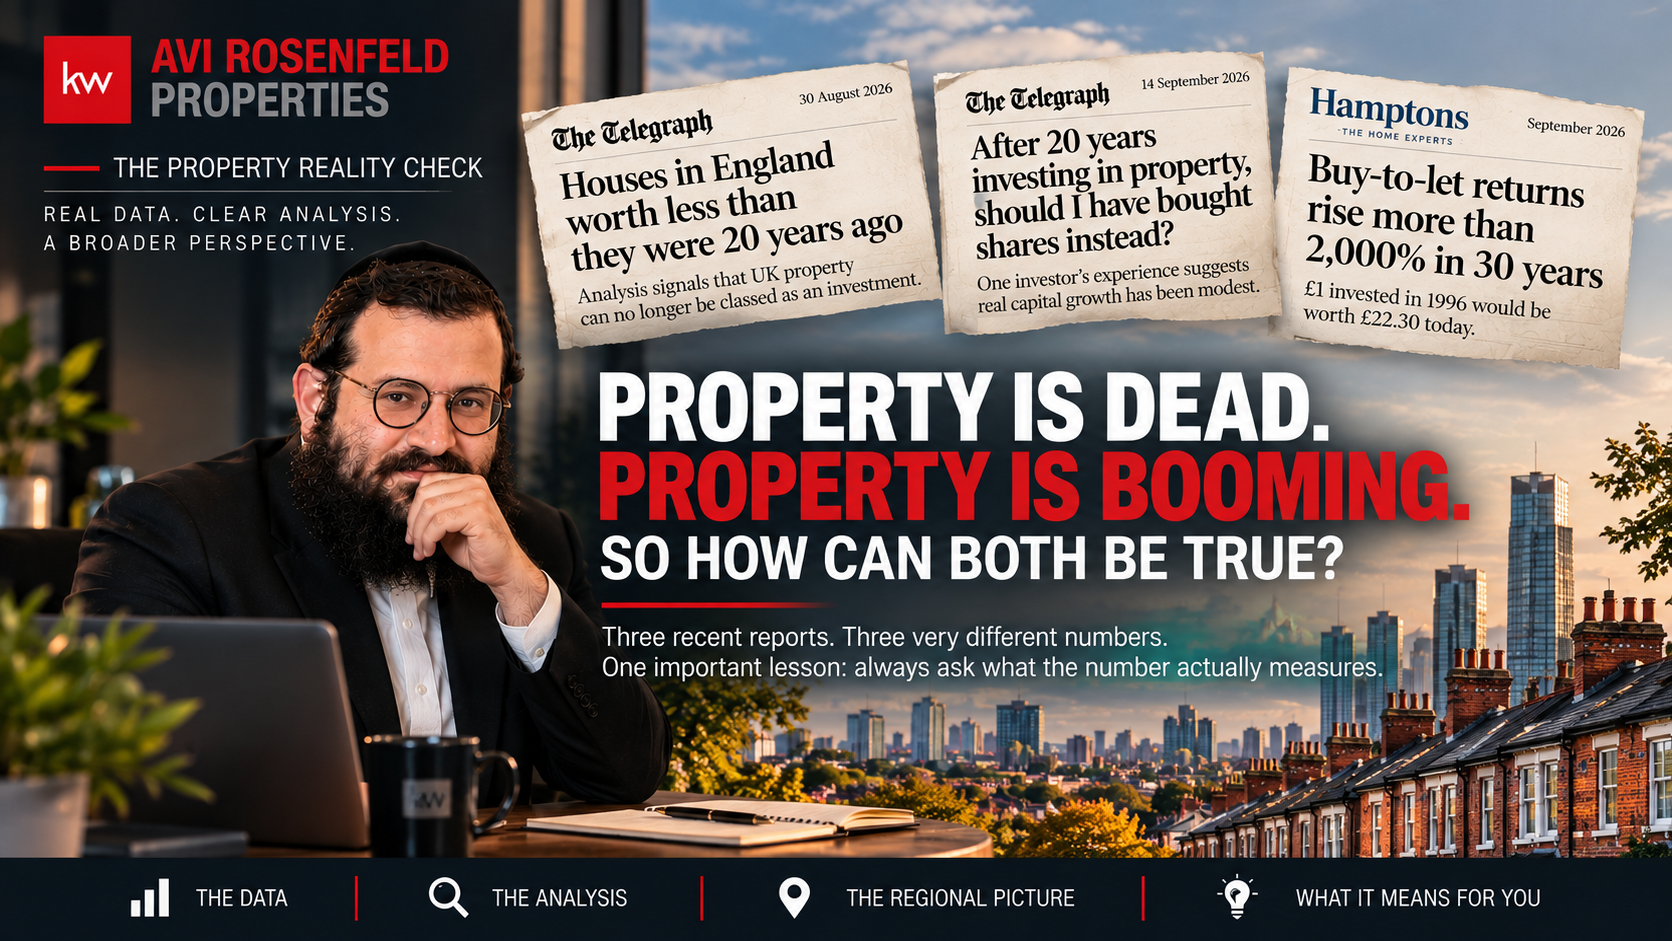
Three recent reports. Three very different numbers. One important lesson:
Always ask what the number actually measures.
I’ve been reading three property stories recently and, at first glance, they seem to be telling completely different stories.
One says houses in England are worth less in real terms than they were 20 years ago. Another asks whether a property investor would have been better off buying shares instead. Then Hamptons publishes research saying that £1 invested in buy-to-let in 1996 would have become £22.30 by 2026.
So which is it?
I think the answer is quite simple.
Look at what is actually being measured.
- House prices alone
Telegraph reported on 30 August that an average home in England sold for £293,262 in June 2026. It compared this with an average price of £296,179 in July 2006, after adjusting the 2006 figure for inflation. So once you allow for the changing value of money, the average English house had made virtually no real progress over that period. That sounds pretty bad for property. And it is an important number. But it is measuring the value of the property itself It is not measuring the rent that property may have produced along the way.
- Then another Telegraph article looked at one investor’s portfolio
Two weeks later, The Telegraph published an article from its ""Secret Landlord". His numbers were interesting. Over 20 years his portfolio had increased in value by 95.8% in nominal terms compared with 71.6% for England over the same period. That sounds much better. But when he broke the numbers down, the nominal annual return was about 3.2%. After inflation, the real return was only 1.6% a year. He also calculated that only 45% of his "profit" was real with the remaining 55% representing inflation. But there is another big point here. He was looking at the capital side of the investment. Rental income was not included in that headline capital-return calculation. He also made an interesting point about mortgages. If you use borrowed money to buy a property, you are not necessarily measuring your return against the full property value. A relatively small increase in the property’s value can represent a much larger percentage return on the cash you actually put in. That is leverage and importantly, leverage can work both ways.
- Then comes the £22.30 figure
Now we get to the Hamptons research published on 21 September. This time, we are measuring something completely different. Hamptons looked at "total investment return", rather than simply house-price growth. Its calculation found that every £1 invested in an average UK buy-to-let property in late 1996 produced £22.30 in total returns by 2026. That is a cumulative return of 2,130%. But the really interesting number is where that return came from. According to Hamptons: 62% came from rental income. 38% came from rising property prices. That changes the conversation quite a bit. Because suddenly we can see how property prices can have relatively modest real growth while the overall investment can still have produced substantial returns.
So are the reports contradicting each other?
Not really. They are answering different questions. One asks: "How much has the property itself increased in value after inflation?" Another asks: “How has one particular investor’s property portfolio performed?”" Hamptons asks: "What was the total return from a model buy-to-let investment when you include rental income as well as capital growth?"
Those are not the same calculation. It is a bit like looking at shares. You can look at the share price or you can look at the share price plus dividends. You would not normally say those are the same measurement. The same applies to property.
There is another reason I think people need to be careful with headlines:
The UK is not one property market.
England as a whole is not Manchester and Manchester is not Salford and Salford is not one single market either.
Different property types, streets, price points, rental markets and buyer demand can produce very different results.
That is why I’m always cautious when I see a headline saying: UK property is up or UK property is down.
The next question should always be:
Where and then over what period and are we talking about capital growth or total return? And what about property as an investment today?
This is where I think the conversation gets more interesting.
The fact that property prices have not produced huge real growth over a particular period does not automatically mean that property was a poor investment.
But the Hamptons figure does not mean that every landlord today is going to turn £1 into £22.30 either. The starting point matters. The location matters. The purchase price matters. The rent matters. The financing matters. And the costs matter.
Most importantly, past performance is not a guarantee of future returns. That is probably the biggest mistake people make when reading figures like these. They see a 30-year return and assume the next 30 years will look the same. We simply don’t know that.
My takeaway
I’m not writing this to tell you that property is better than shares. And I’m not telling you that property is a bad investment either.
I think the bigger lesson is much simpler:
When somebody gives you a property return figure, ask one question first:
""What exactly is included in that number?"" Capital growth? Rental income? Inflation? Leverage? Costs? Taxes? A national average? One investor’s portfolio? A five-year period? A 30-year period? Those details can completely change the story.